


June was another month that absolutely flew by. We returned from our East Coast road trip on the first of the month, and that first weekend was mostly spent unpacking and relaxing before heading back to work the following Monday. In the subsequent weekends we went camping twice and spent another weekend afternoon exploring locally in between a lot of house work.
Vacations
While we spent half of our weekends in June on vacation (plus the Friday traveling home from the East Coast), we spent very little money on actual vacation expenses since the camping nights were either free or $38 at most expensive. One of the trips was of course to the Olympic Peninsula, so there were a couple of ferry fares in there as well. Otherwise, camping is an extremely frugal form of travel, and one of our favorites, be it backpacking, truck camping out in the middle of nowhere, or tent camping in a standard campground.


Food and Drink
Again, this category is artificially high (as is our gas expense) since a large chunk of our spending here was done while on our weekend trips. A good $100+ of gas and the majority of our restaurant spending for the month was done while not at home.
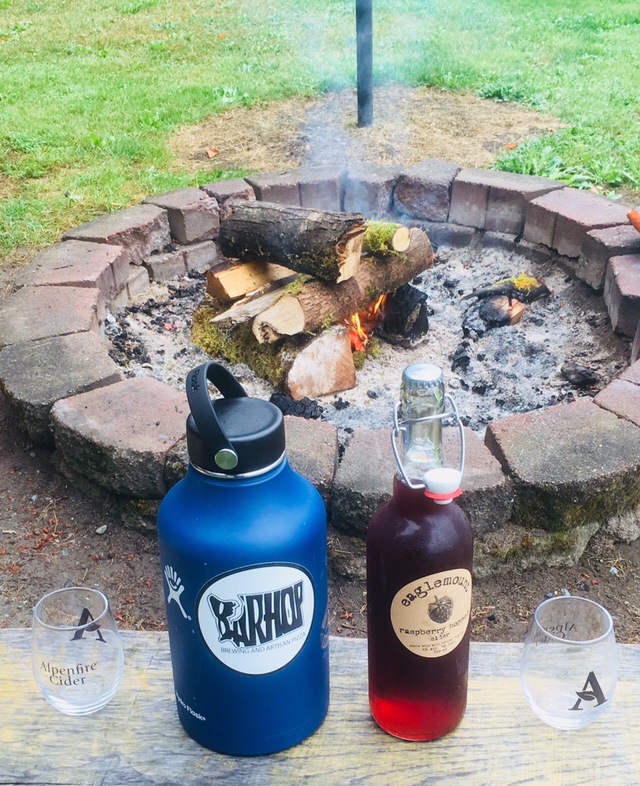
While in the Sequim area this past weekend, we checked out two different cideries and a brewery (combined with a pizza lunch stop), all of which we had never visited before. Local, small batch alcohol is certainly more expensive than the store bought stuff – and obviously more than not drinking at all – but it something we enjoy doing while we travel, so it’s a cost I expect to stay in the long run.
Could we shave off a number of years until we reach financial independence if we cut out most of our discretionary spending? Yes, but our goal is to spend on what we value, not just cut to the bone to save another dollar. As long as something doesn’t completely blow our financial plans (like the $90k truck my husband jokes about constantly…) then I don’t see an issue with choosing to spend our money that way.

Vehicle Expenses
Or should I say, vehicle expense. Outside of gas, we only had one transportation expense for the month. Unfortunately, that expense was truck tires, and they aren’t cheap. We knew this expense was coming, so it wasn’t a surprise, but it’s still rough having to drop close to four figures in one go on a vehicle, regardless of what for. I realize we could easily have $750+ in car payments every month between the two of us, but as someone who has never spent a lot on vehicles, big ticket maintenance items always sting a little.
One of the biggest immediate perks to having a great savings rate every month is that there’s a good buffer for cash flowing a larger expense in any given month. When we were spending more, paying for truck tires, a vet visit, and a couple of weekend trips may have been too much to happen all in one month.
Instead of having to budget for sinking funds, or use our emergency fund as a more all purpose fund for larger expenses, we now simply cash flow the bigger ticket items and just have a smaller savings rate for the month.
Emergency funds and a cash buffer in the bank is still something we have for peace of mind, but it would have to take a significantly large emergency to not be able to cover it in a normal month, which feels really good. Regardless of full financial independence goals, living well below your means is just a less stressful way to live month to month.


Miscellaneous Expenses
This month, our miscellaneous expenses include soccer classes at preschool for our son, a couple of small Father’s Day gifts, and an ebook off of Amazon for my husband (don’t bother trying to tell him you can check them out from the library, he likes to own them, and I don’t mind the expense because it means he is reading).
June 2018 Spending (Excludes Mortgage + Daycare)
| Jan 2018 | Feb 2018 | Mar 2018 | Apr 2018 | May 2018 | Jun 2018 | |
| Groceries | $462.37 | $491.07 | $497.53 | $343.37 | $658.76 | $353.25 |
| Restaurants | $406.95 | $440.00 | $243.63 | $583.75 | $1,040.03 | $529.21 |
| Fast Food | $19.48 | $5.72 | $80.34 | $83.54 | $120.78 | $75.89 |
| Gym | $17.84 | $17.84 | $17.84 | $17.84 | $17.84 | $17.84 |
| Gas | $110.10 | $120.23 | $262.00 | $199.76 | $263.60 | $242.89 |
| Car/Transit | $28.11 | $166.00 | $60.00 | $0.00 | $30.00 | $737.53 |
| Utilities | $218.01 | $370.27 | $223.99 | $366.55 | $200.25 | $266.25 |
| Pet Care | $228.28 | $209.95 | $769.90 | $221.65 | $273.96 | $277.56 |
| Vacations | $588.69 | $274.65 | $129.51 | $297.44 | $971.66 | $148.00 |
| Miscellaneous | $53.00 | $256.28 | $823.58 | $177.49 | $354.68 | $164.62 |
| Total | $2,132.83 | $2,352.01 | $3,108.32 | $2,291.39 | $3,931.56 | $2,813.04 |
| Savings Rate | 53% | 51% | 61% | 53% | 44% | 44% |
| Excluding Mortgage Principal | 47% | 45% | 57% | 47% | 39% | 38% |
I was actually pretty frustrated with myself when I initially calculated our numbers this month since we missed that 50% savings rate again, but since I agreed to share my numbers accurately here every single month, I made the time to go through the details, knowing that what gets measured gets done. Through the process of writing this post though, I’m realizing we still did quite well and it isn’t fair to beat myself up for coming in a little short. If you exclude the cost of the truck tires, I would be quite happy with where this month landed (52% savings rate if car maintenance is excluded). Between a big trip and vehicle maintenance two months back to back, it’s shaping up to be an expensive summer – though much less expensive than last year.
I don’t see any big expenses on the horizon for July, so hopefully we will be solidly in the 50%+ savings rate camp this month. If I average out over the first six months, we’re at a 51% savings rate, so as long as the next six months look similar, we should hit that big goal for the year. Goals should be difficult to achieve, but possible, in order to push yourself, and I feel like I judged this one pretty well.
How is 2018 shaping up for you? Do you have any big financial goals for the year?